
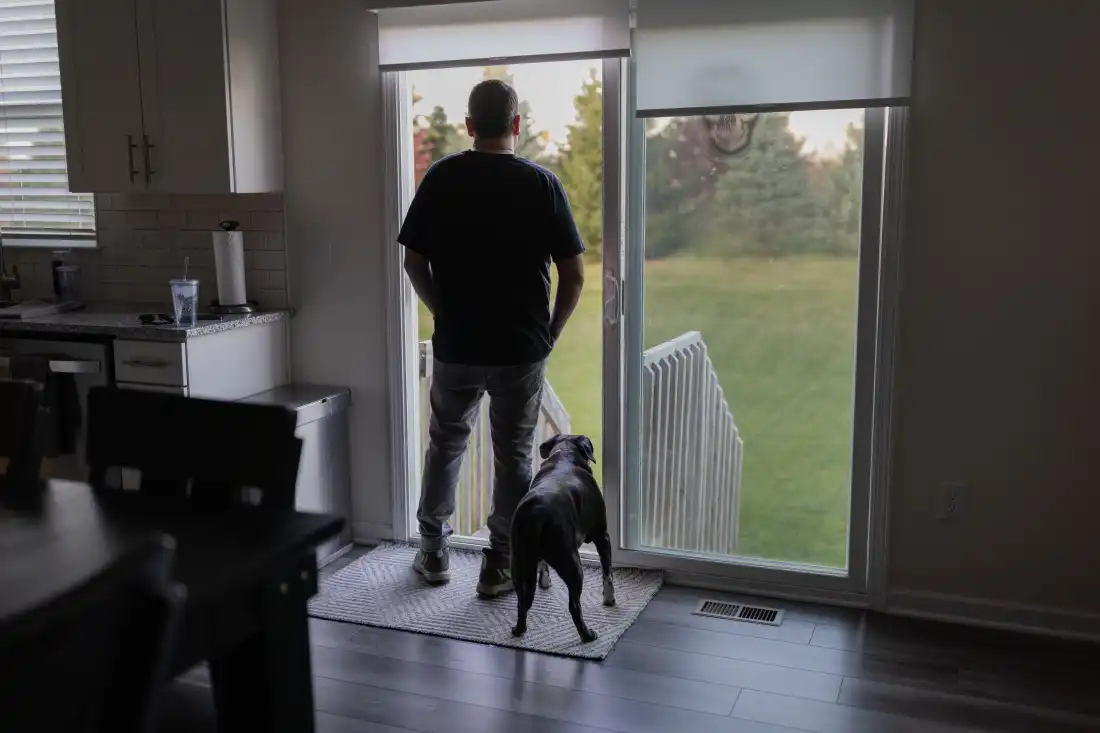
Scott Boyd, an Army veteran, stands with his dog, Jessi, at his home near Columbus, Ohio. A loan adjustment increased his VA home loan payment by almost $1,200 monthly. Due to his military intelligence background, Boyd requested NPR to exclude his face from photographs.
Military veterans with VA-backed mortgages face higher interest rates and monthly payments since the Trump administration ceased a low-interest initiative aiding them. According to an NPR inquiry obtaining unreported Department of Veterans Affairs data, over 15,000 veterans who modified their loans after financial challenges experienced monthly payment surges exceeding $150. More than 700 veterans encountered increases over $1,000.
Lenders modify loans to aid homeowners in catching up on missed payments, usually altering terms to lower or sustain payments based on affordability. This standard does not apply to VA loans because the VA stopped the program. NPR discovered 63% of veterans receiving loan modifications experienced payment hikes, compared to 2% for modifications by Fannie Mae and Freddie Mac, covering most U.S. mortgages.
California Democratic Rep. Mark Takano, the House Veterans’ Affairs Committee ranking member, criticizing the situation said, “This is the height of insanity.” Veterans already financially distressed now shoulder an additional financial burden.
Scott Boyd’s past offers context. His father’s cancer led Boyd to enlist in the military as a teenager to assist his family financially. He served in infantry and, later, Army intelligence. Upon leaving the service in 2002, he pursued a tech career. Using a VA home loan, he purchased a house near Columbus, Ohio, in 2021, securing a favorable interest rate.
However, job loss in a layoff and PTSD-related issues forced Boyd to seek treatment at the Dayton VA hospital, resulting in mortgage payment delays. Boyd and fellow veterans now face costlier modified home loans. Boyd’s lender initially assured him of support through a VA loan forbearance program, later revealed to be non-existent due to the Trump administration shutting down the Veterans Affairs Servicing Purchase (VASP) program. Boyd now pays $1,181 more monthly.
California Rep. Takano emphasized that the VA home loan program should alleviate rather than exacerbate veteran stress.
Illinois Republican Rep. Mike Bost, House Veterans’ Affairs Committee chairman, and Wisconsin Republican Rep. Derrick Van Orden, a committee member advocating for VASP’s termination, did not respond to NPR’s requests for comment.
The VA stated it supports veterans in retaining homeownership through payment forbearance, loan modifications, and customized repayment plans. Before termination, VASP aided veterans by consolidating missed payments into loans with low 2.5% interest rates. Mortgage industry representatives and housing groups advised against halting the program without a replacement, as veterans would have only high-interest-rate options.
Foreclosures soared post-VASP shutdown. Industry experts warned of more potential foreclosures unless protective measures were instated. Rep. Takano noted Congress could intervene to support affected veterans.
Boyd resides with his partner and four children, seeking stability and educational opportunity through homeownership. He supports his family, despite increased payments after a loan modification left him with extended 40-year terms at higher interest rates. Two weeks post-modification, the VA introduced a Partial Claim Program (PCP), allowing service members to maintain original terms with consistent payments, yet it did not retroactively apply to earlier cases.
Boyd expressed disappointment in receiving lesser terms than those who never served, feeling unrecognized for his military contributions. “I really felt hurt more than anything,” Boyd stated. “Everything that I’ve done for this country…it’s come down to, ‘Yeah, I’m sorry — there’s nothing we can do about it.'”